Should You Save Money or Pay Down Debt First? Here’s How to Balance Both
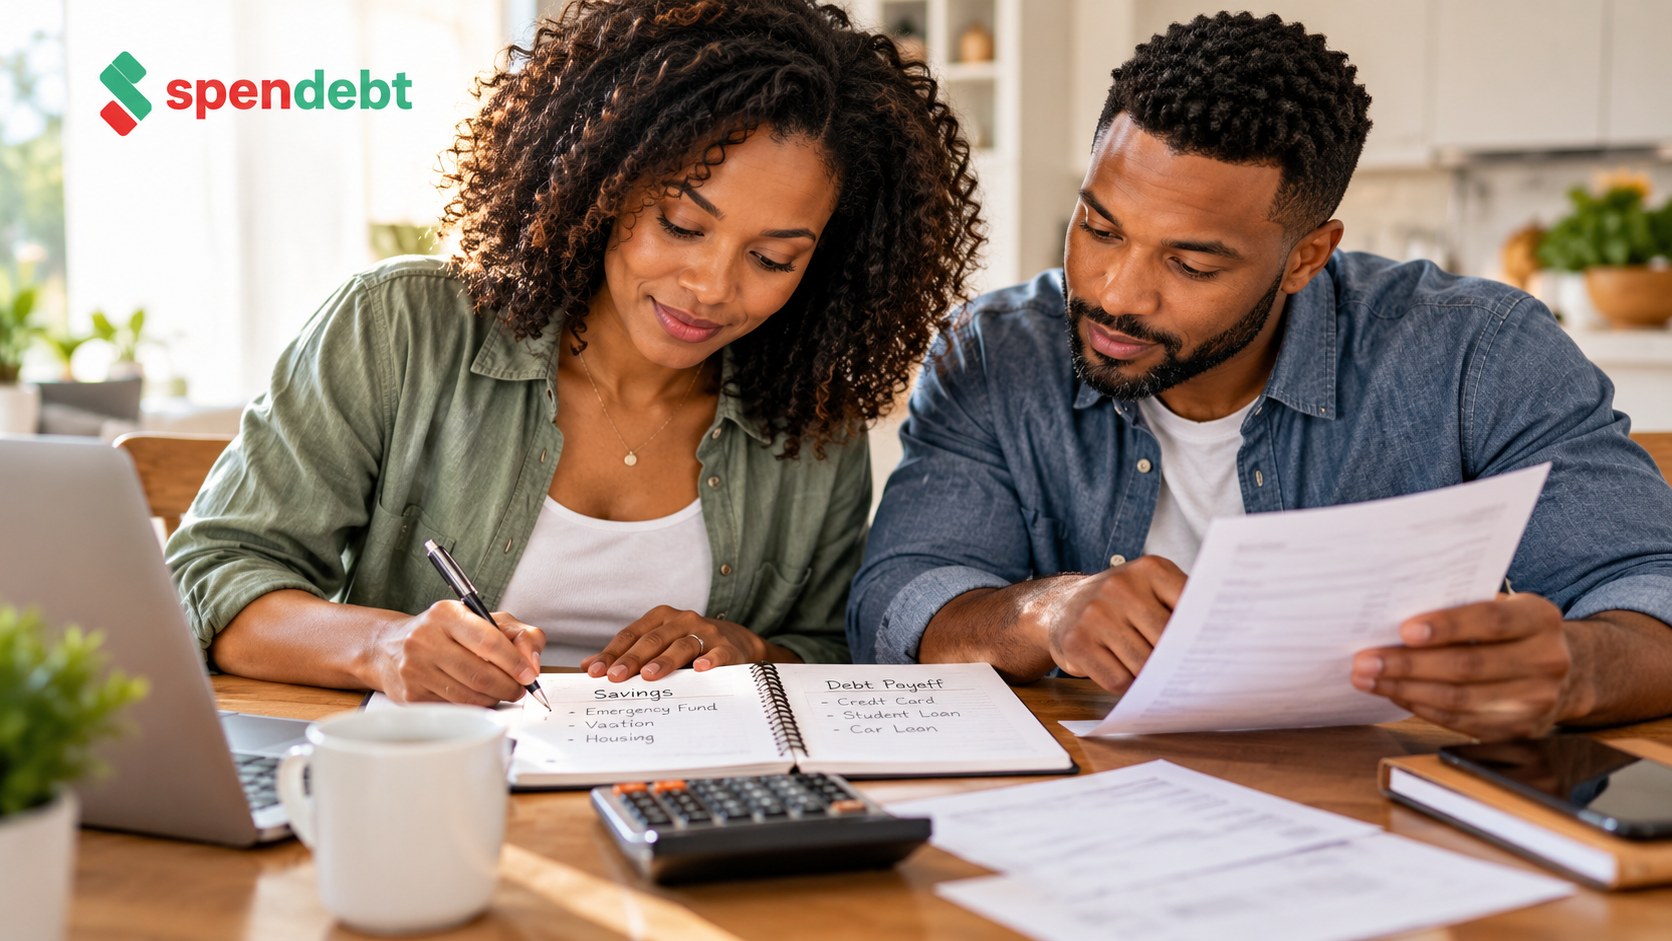
You’ve got a little money left over this month. Should you save it or put it toward what you owe? It’s a question many households face. Saving feels important because life happens. Paying down debt matters because interest can make balances more expensive over time. The good news? It doesn’t always have to be an either-or decision.
First, Protect Your Essentials
Before deciding what to do with extra money, make sure you’ve accounted for essentials such as housing, food, utilities, transportation, and required payments. If you’re struggling to meet a required payment, contact the creditor and ask about available options. The goal is to create a plan that helps you move forward without making today’s finances harder to manage.
Why Having Some Savings Matters
Imagine you’re making steady progress on a credit card balance when your car suddenly needs repairs. Without emergency savings, you may have to put that expense on the same card you’re trying to pay down. A small cash cushion can help you handle unexpected costs without immediately taking on more debt. You don’t have to build a perfect emergency fund overnight. An initial savings goal that fits your circumstances is a reasonable place to begin.
Why Extra Payments Matter, Too
When you carry interest-bearing debt, paying more than the required minimum can help reduce your balance and the amount of interest you pay. High-interest balances can be especially costly to carry over time. That makes additional payments valuable when your budget allows them. But sending every available dollar toward debt while keeping no emergency savings may leave you vulnerable to the next surprise expense.
Consider Making Progress on Both
One practical approach is to work toward a starter emergency fund while continuing to meet required debt payments. As your savings become more stable, you can choose to direct additional funds toward higher-interest balances. The balance between saving and repayment will depend on your income stability, existing savings, debt costs, and financial priorities. There isn’t one percentage or dollar amount that works for every household.
Make Extra Payments Feel More Manageable
This is where small, consistent contributions may help. SpenDebt’s Everyday Micropayments lets you choose a fixed amount associated with eligible everyday transactions. Those amounts accumulate and are paid toward your selected account. It’s one way to make additional payments without relying entirely on a large lump sum. Of course, extra contributions should fit your budget, and you’ll want to consider the service’s subscription cost.
Financial Progress Is Bigger Than One Balance
Reducing what you owe is important. So is being prepared when life doesn’t go according to plan. A thoughtful financial strategy can make room for both.
Start where you are. Protect what matters. Keep making progress.
Interested in adding manageable extra payments to your financial routine? Discover SpenDebt.
Everyday Micropayments. Measurable Progress.
This article provides general financial education, not individualized advice. For additional guidance, see the Consumer Financial Protection Bureau’s emergency savings resource.